Fabric for sponsor banks
Fabric · Nucleus BankOS modulePartner programs the bank can supervise.
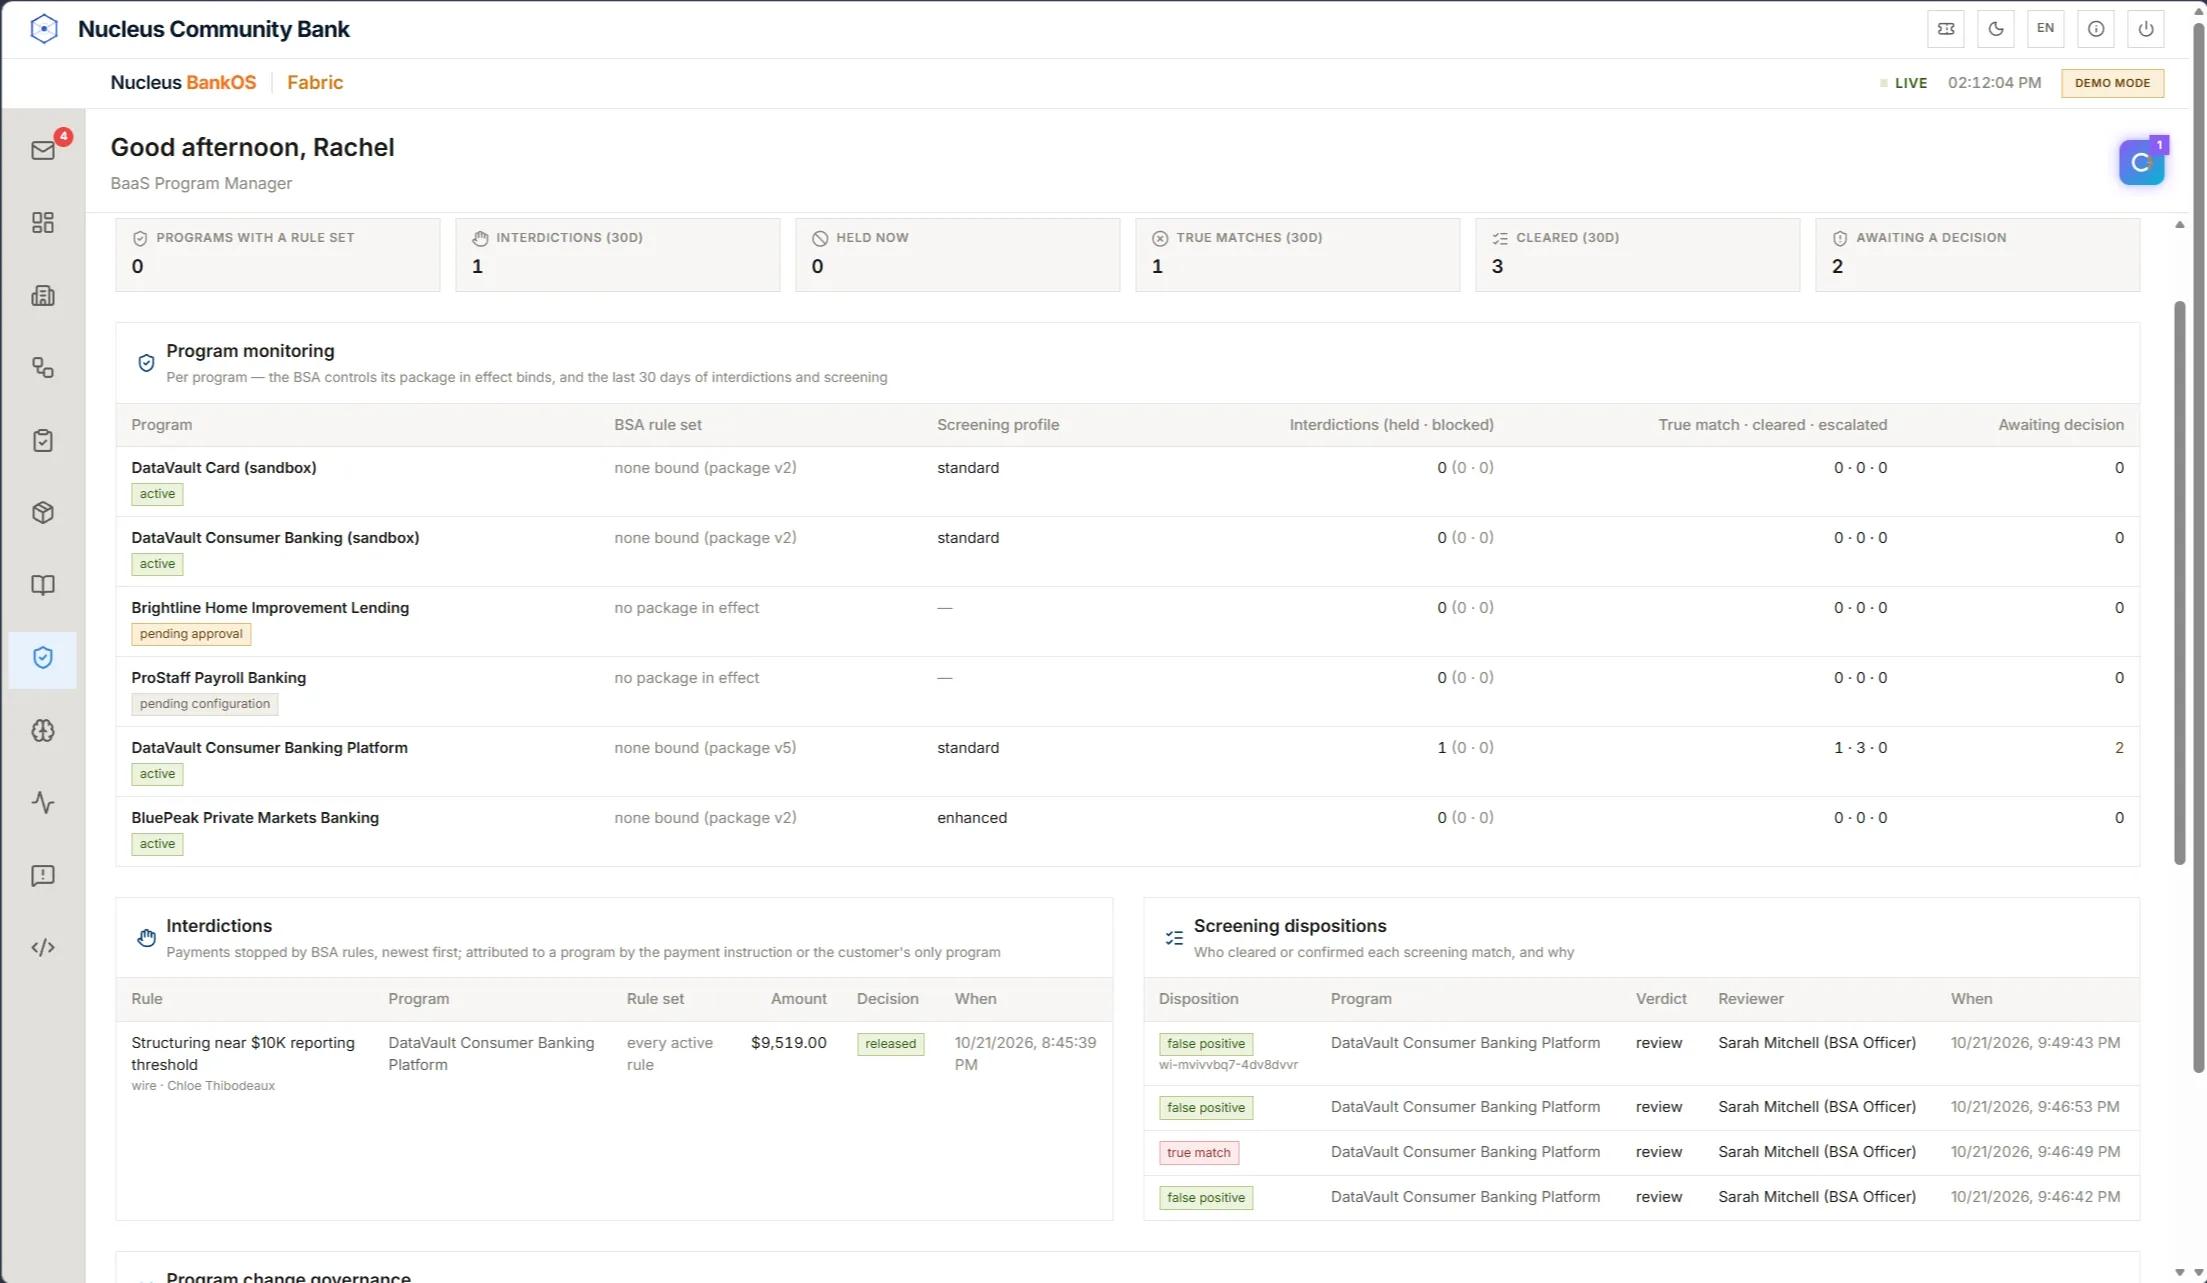
A sponsor bank is the chartered bank that holds the deposits and carries the regulatory responsibility for a fintech partner’s accounts and cards. Fabric gives it isolated programs, limits it sets, the KYC decision and an append-only record of every partner action.
At a glance
- Limits
- Set by the bank; enforced on every write
- KYC decision
- Platform or bank vendors, never the partner
- Isolation
- Each partner in its own program
- Keys
- Issued, rotated and revoked by the bank
- Monitoring
- One view across every partner program
- Records
- Append-only, including partner-side events
Specifications
Who controls what
The bank owns authority, capability and limits; the partner operates inside them.
| Create and configure a program | Bank |
|---|---|
| Set the system of record and limits | Bank |
| Issue, rotate and revoke keys | Bank; the partner can request |
| Grant API scopes | Bank; the partner can request |
| Register webhook endpoints | Bank or partner, within the grant |
| Provision sub-programs | Partner, within the grant; the bank approves |
| Decide KYC and KYB | Platform or the bank’s designated vendors |
| Transaction limits | Per-transaction ceilings, daily and velocity caps; raising one is a logged action |
|---|---|
| Approval queue | Money movement above the auto-release ceiling waits for a person |
| Inline compliance rules | Violations raise a flag and can route to the bank for review |
| Cross-partner monitor | Alerts from every program in one place |
| Financial-crime monitoring | Screening and transaction monitoring in DarkMatter, on the same core |
| Audit trail | Every API call, money movement, decision and configuration change, append-only |
| Partner write-back | Partners must log access, security and error events to the same trail |
| Key revocation | Immediate and total; rotation can overlap for a no-outage cutover |
Questions
What people ask
What is a sponsor bank?
A sponsor bank is the chartered, insured bank behind a banking-as-a-service program. It holds the deposits, issues the accounts and cards, and answers to regulators for the program, while the partner provides the brand and the app.
What do regulators expect from a sponsor bank?
The 2023 interagency guidance on third-party relationships expects banks to oversee partners in proportion to the risk, as they would their own operations. In practice that means knowing each end user’s balance, controlling onboarding and limits, and being able to show examiners what every partner did.
Can a partner change its own limits or scopes?
No. Limits and scopes are set by the bank administrator; a partner can request a change but cannot make one. A sub-program can only narrow what the bank granted its parent.
How does the bank see activity across partners?
A single compliance monitor shows alerts from every program, and screening and transaction monitoring run in DarkMatter on the same core. A pattern spanning two partners is visible to the bank rather than split across two vendors.
What happens if a partner’s key is exposed?
The bank revokes it, which is immediate and total, and issues a new one. Planned rotations can overlap old and new keys for a cutover window, so there is no outage.
Related
Keep reading
Module
Fabric
Banking-as-a-service on Nucleus BankOS.
For partners
Embedded deposits
White-label accounts, sub-ledgers and FBO structures on the bank’s core.
For developers
Partner APIs
What partners integrate, how they connect, and how calls are governed.
Add-on
DarkMatter Synergy+
Connected fraud, cyber and BSA cases.
Grow partner deposits without exporting the risk.
A working session on your partner program, your controls and your examiners’ questions.