AI-driven lending
Lend like a bank ten times your size.
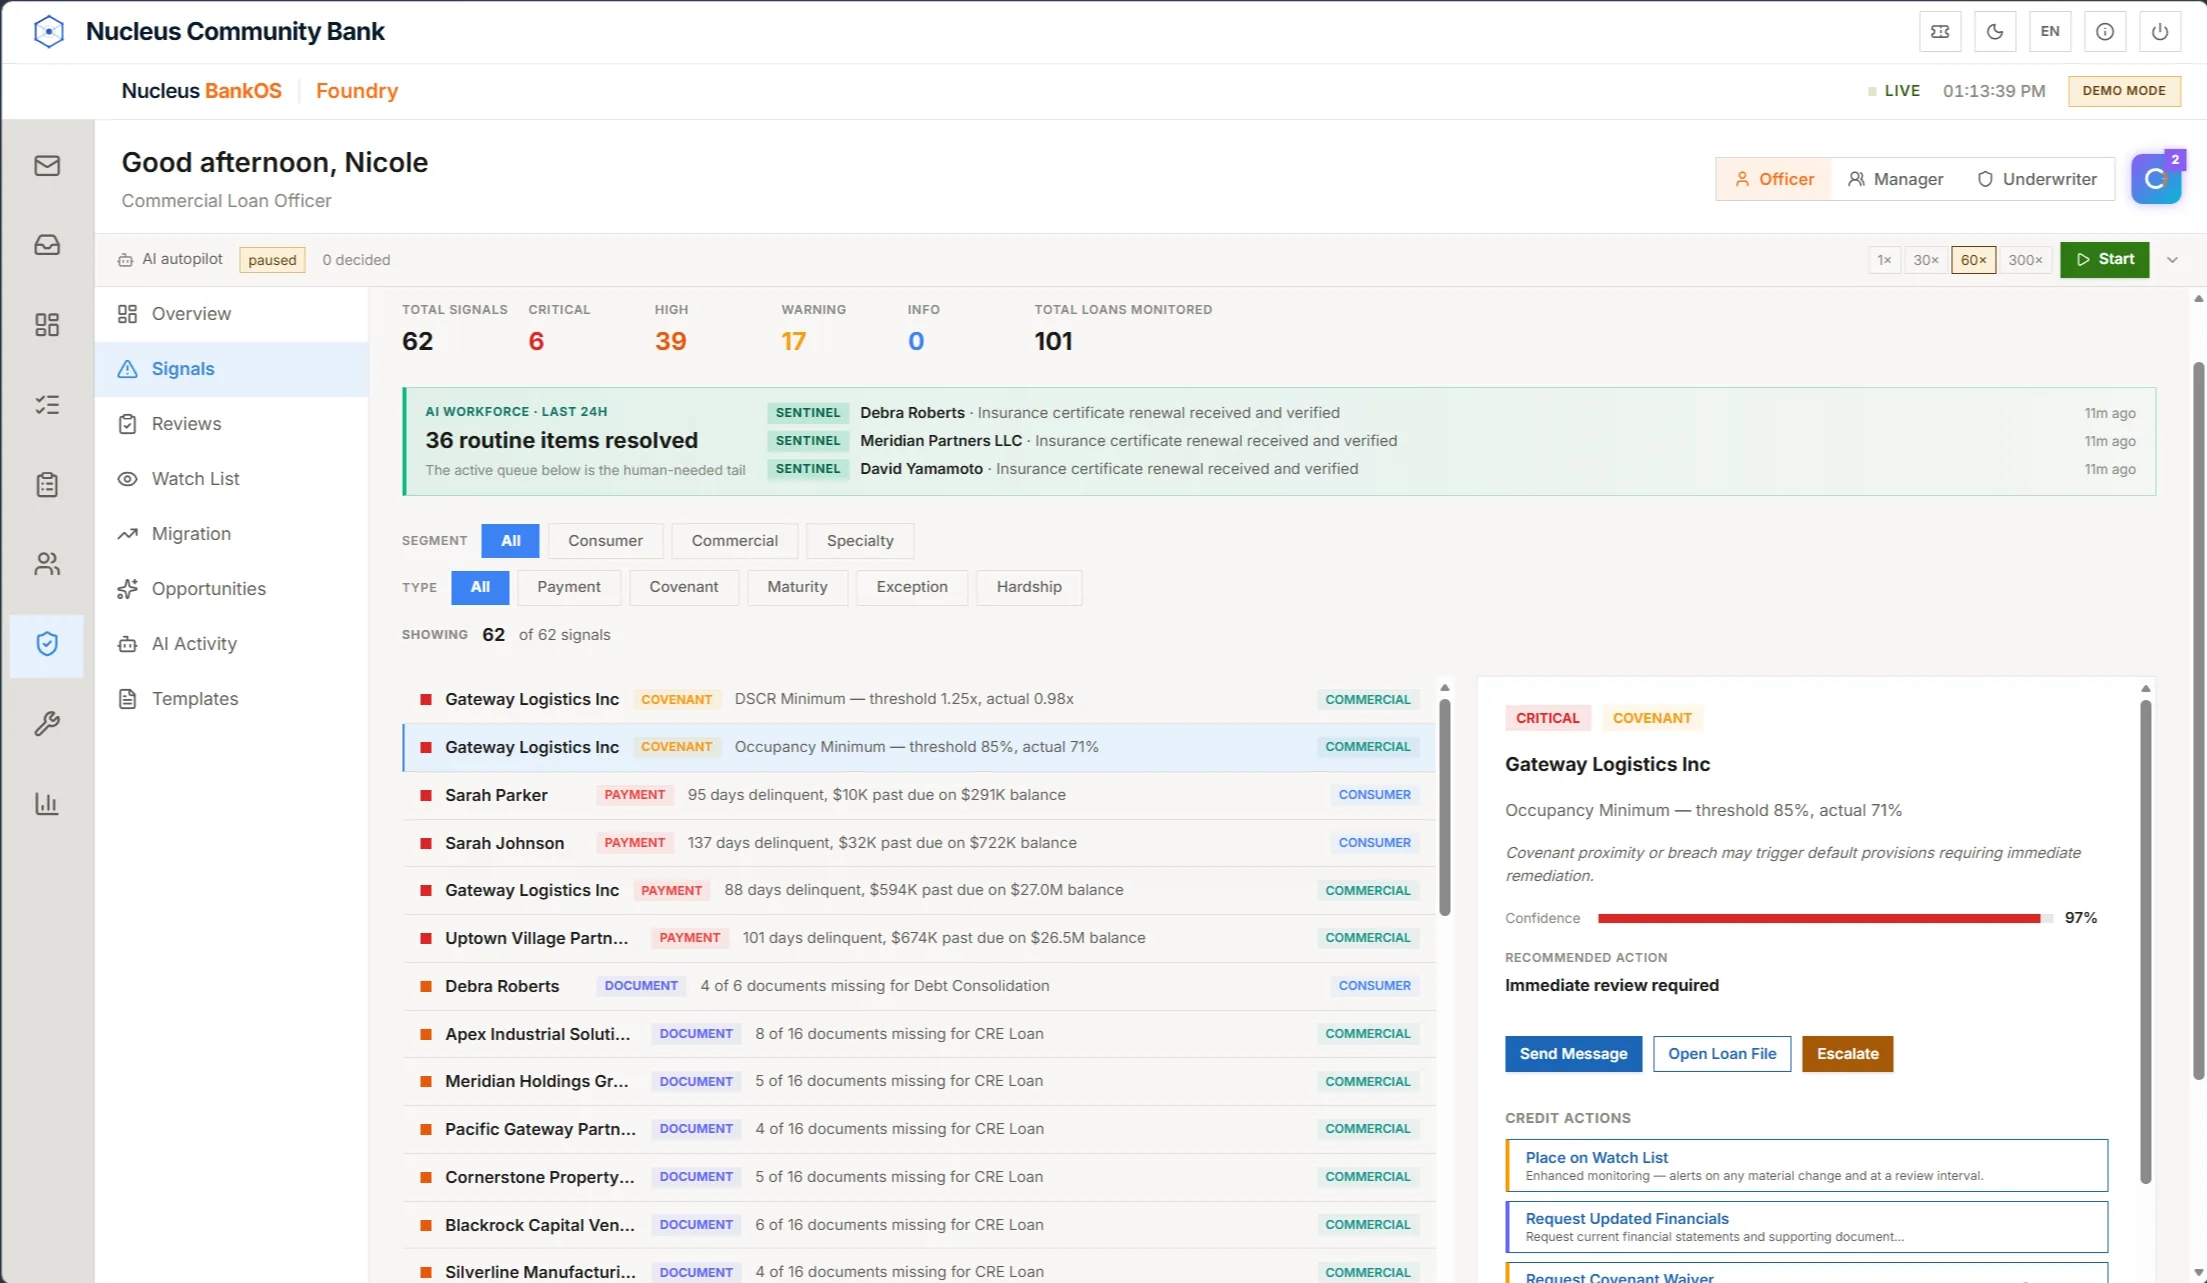
AI-driven lending is how community banks scale credit without scaling headcount: Foundry runs every application through one decision engine on the bank’s policy, and AI prepares the analysis within limits the bank sets.
The problem
Lending capacity is capped by headcount.
One rigid scorecard, and a change request to adjust it.
Decisions that are hard to explain at exam.
Adverse action stitched together by hand.
The workflow
One decision engine, origination to the ledger.
The officer works exceptions, not queues
Applications inside policy bands are decided by the bank’s rules; gray-zone deals route to an underwriter with the analysis already done.
Learn moreAI prepares, policy decides
CLARA AI Advanced spreads statements, reads documents and checks covenants within limits the bank sets. Anything outside tolerance escalates.
Learn moreBooked to the GL at funding
Every funded loan writes its record and GL postings to Nucleus BankOS in real time.
Retail to commercial on one engine
Consumer, commercial, CRE and specialty structures run through the same gate.
Adverse action built in
Declines route to the responsible officer, with ECOA notices generated at decline.
Risk signals in the file
DarkMatter Synergy+ correlates fraud and BSA signals with the credit file.
Model it, then see it
Test it against your numbers
Build your business case
Model lending volume, cycle time and operating cost at your institution’s scale.
Side-core and full-core results shown separately, as ranges.
Illustrative scenarios: a hypothetical institution with modeled outcomes, not a customer deployment.
Questions
AI-Driven Lending: what banks ask
How does AI-driven lending differ from traditional credit scoring?
Traditional scoring applies one rigid rulebook to a thin set of bureau attributes. On Foundry, one decision engine applies the bank’s own policy consistently, explains every outcome and books the loan to the core GL in real time. The bank, not a black-box vendor, sets the policy and keeps the audit trail.
Can community banks defend AI lending decisions at exam?
Yes. Every decision is logged with its inputs, the policy applied and the result, and can be replayed. Examiners can walk individual decisions or sample populations without the bank reconstructing anything by hand.
Does the AI approve loans?
No. The bank’s credit policy decides; AI prepares the analysis and acts only within the authority and tolerance limits the bank sets. Anything outside those limits goes to the assigned officer.
Does AI-driven lending work for commercial and CRE, not just consumer?
Yes. Foundry handles consumer, commercial, CRE and specialty structures through the same decision gate — 28 structures in total — with the same explainability and GL integration.
What happens to adverse action notices?
Declines route automatically into an adverse-action pipeline assigned to the responsible officer, with ECOA notices generated at decline and sent at close.
Do we have to replace our core to use AI-driven lending?
No. Foundry can run alongside an existing core through Nucleus BankOS side-core deployment, so the bank can evaluate the workflow without a full core replacement on day one.
Bring the workflow you want to change.
A working session with the founders on your use case, your core and your first step.