Open banking & payments
Modern payment rails, without spending millions to add them.
Open banking and payments is how community banks run modern rails and API delivery on the same core: Vault settles FedNow, RTP, ACH and wire straight to the live ledger, and Fabric exposes governed APIs under the bank’s consent controls.
The problem
Every rail is another integration to reconcile.
Each rail a separate vendor integration.
Reconciliation lag and break queues.
Open-banking APIs as an afterthought.
The workflow
Rails and APIs on the live ledger.
Governed open-banking APIs
Fabric provides account access, payment initiation and data sharing on the customer-keyed core.
Learn moreFour rails, one surface
FedNow, RTP, ACH and wire run through Vault and settle straight to the live ledger.
Learn moreLiquidity in real time
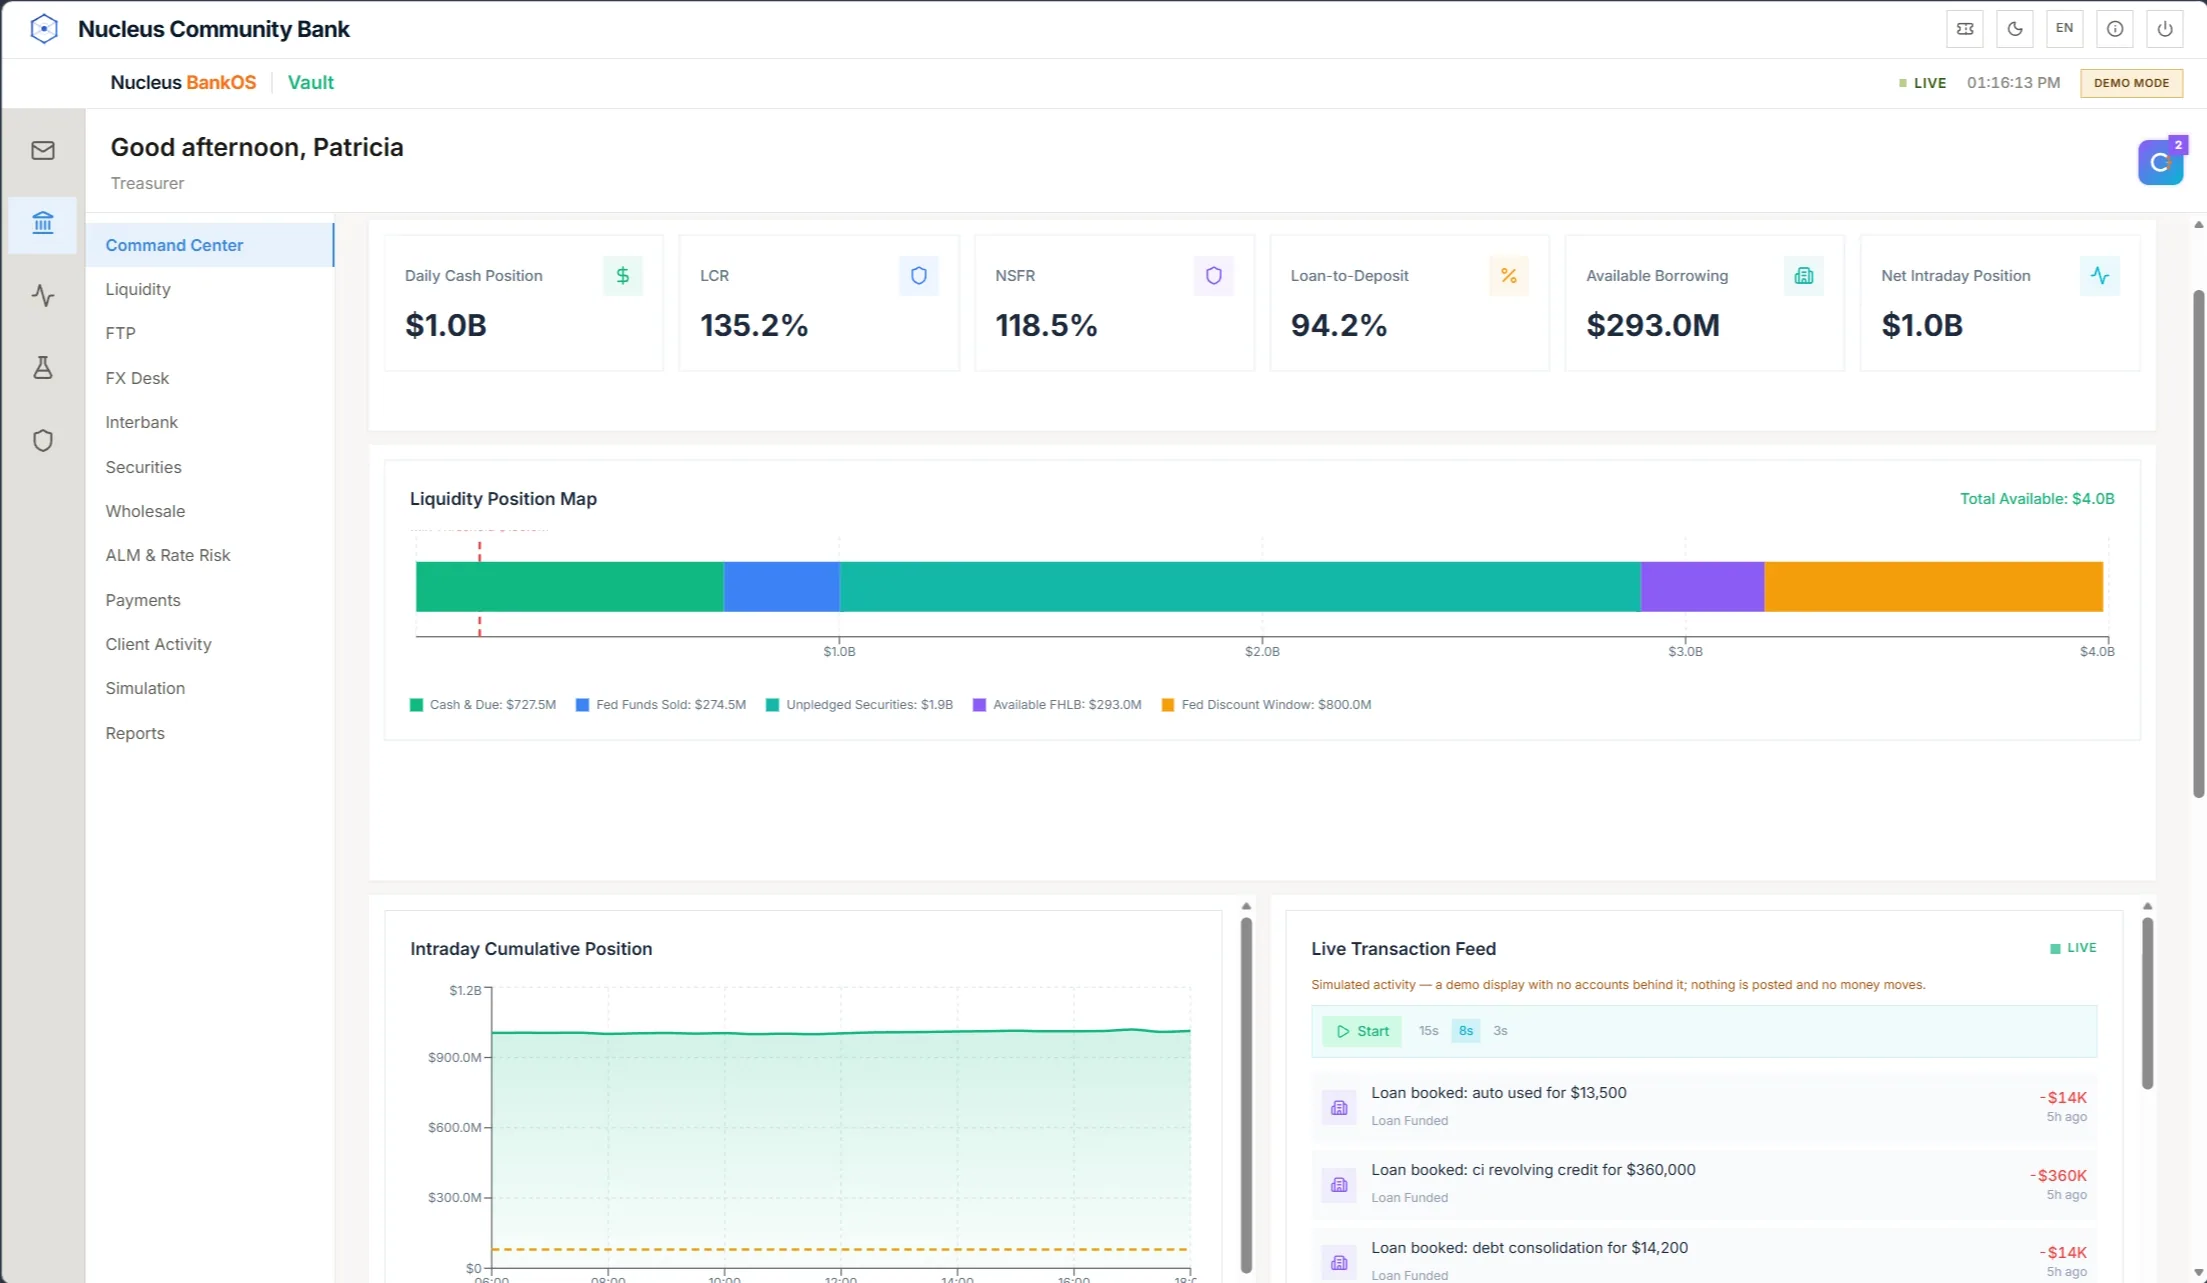
Live FX and intraday liquidity, from the same positions the payments post to.
Consent the bank controls
Authentication, scopes, consents and revocation are set by the bank; every call is logged with its consent state.
Payment risk correlated
DarkMatter Synergy+ reads payment activity alongside fraud, BSA and cyber signals.
Learn moreModel it, then see it
Test it against your numbers
Build your business case
Model the payment-hub, integration and reconciliation cost you carry today.
Side-core and full-core results shown separately, as ranges.
Illustrative scenarios: a hypothetical institution with modeled outcomes, not a customer deployment.
Questions
Open Banking and Payments: what banks ask
Does adapfin support FedNow, RTP, ACH and wires?
Yes. FedNow, RTP, ACH and wires settle straight to the live ledger on Nucleus BankOS through Vault, with no reconciliation gap between rail and core.
How is this different from a separate payments hub?
A separate hub is another system to integrate and maintain. On adapfin the rails are native to the core, so a payment posts to the customer’s balance and the GL in real time, not after batch reconciliation.
How does API delivery for open banking work?
Fabric provides governed APIs for account access, payment initiation and data sharing on the same core that runs the rest of the bank. The bank can support partner programs and aggregators without bespoke integration work for each.
Can we control which third parties access data?
Yes. The bank controls authentication, scopes, consents and revocation through Fabric’s program-level controls, and every API call is logged with its consent state.
Is payment risk evaluated in real time?
Yes. DarkMatter Synergy+ correlates payment activity with fraud, BSA and cyber signals in real time on the same ledger, rather than in a separate scoring system.
Bring the workflow you want to change.
A working session with the founders on your use case, your core and your first step.