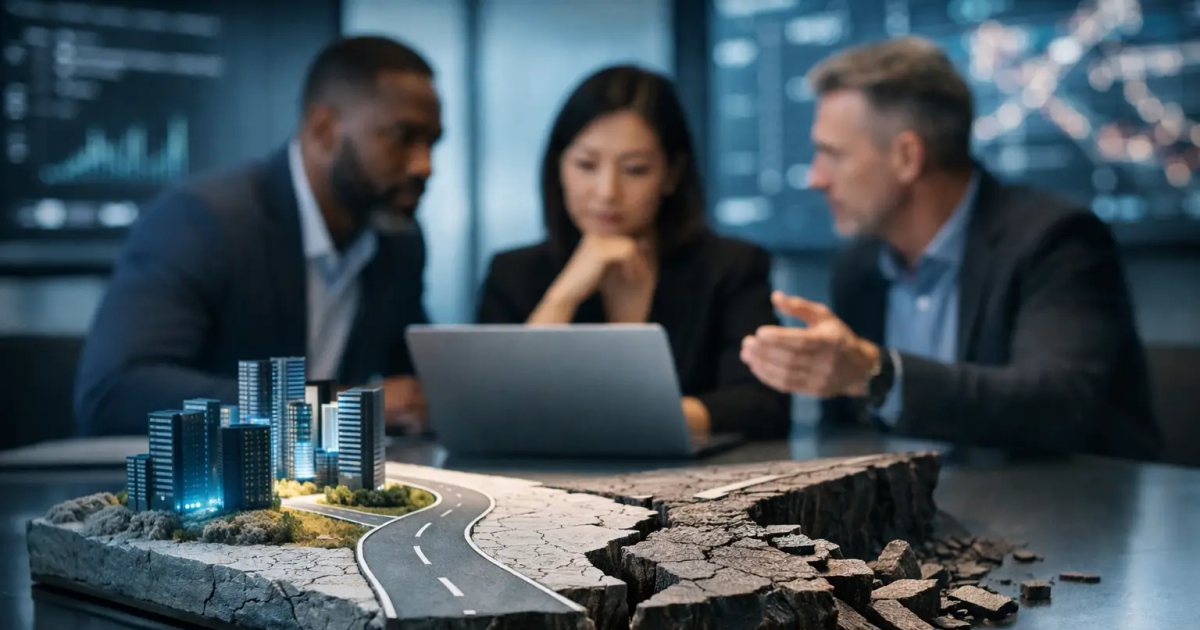
Banks spend months negotiating core pricing, conversion fees, account minimums, and contract terms. Those costs are visible, which makes them easier to compare.
The more consequential cost is often left out of the analysis: what will the institution pay every time it needs to change?
A core banking platform can have competitive licensing and still be expensive to operate. If launching a deposit product requires vendor development, modifying a workflow requires a professional-services engagement, or accessing customer data requires another integration, the bank continues paying long after implementation.
The real economic test of core banking software is how much it costs the institution to act.
Purchase Price Is Only the Beginning
Traditional total-cost-of-ownership models focus on licensing, hosting, implementation, support, and scheduled upgrades. Those costs matter, but they do not capture the operating burden created by the platform.
Consider what happens when a bank changes a product. The core may need new account rules. Digital banking requires updated screens. Disclosures and communications must change. Fraud, AML, accounting, reporting, and servicing teams need corresponding logic. Data must flow correctly among every affected provider.
In a unified environment, these changes can move through shared data, workflows, permissions, testing, and approvals. In a fragmented stack, the bank coordinates multiple vendors, implementation schedules, data mappings, and release cycles.
The cost appears in several places:
- Vendor development and professional-services fees
- Internal technology and operations labor
- Expanded testing and reconciliation
- Manual work created by incomplete integrations
- Delayed product revenue
- Additional controls needed to manage system gaps
- Support and incident-management complexity
These expenses rarely appear together on a core invoice. They are distributed across departments, projects, vendors, and missed opportunities. That makes them easy to underestimate and difficult to eliminate.
The Cost of Change Compounds
Imagine that a bank wants to launch a new deposit product for a specific customer segment. The business decision may involve pricing, eligibility, limits, fees, disclosures, and relationship incentives.
The technology effort can reach much further. The institution may need changes across the core, mobile and online banking, account opening, fraud monitoring, AML rules, statements, accounting, customer service, reporting, and data analytics.
If those systems operate independently, a straightforward product idea becomes a coordination program. Each provider introduces its own requirements, schedule, testing process, and interpretation of the data. A delay in one system can postpone the entire launch.
The same problem affects everyday operations. Changing a transaction limit, adding an approval step, modifying a lending workflow, introducing a payment rail, or responding to a regulatory requirement can trigger another round of vendor dependencies.
Over time, banks begin making strategic decisions around what their technology providers will permit. Products remain unchanged because modifying them is too difficult. Manual processes survive because replacing them requires another project. Promising partnerships are delayed because integration capacity is already committed elsewhere.
Technology stops supporting strategy and begins defining its boundaries.
The cost of change also compounds through workarounds. A temporary spreadsheet becomes a permanent control. A one-time data extract becomes a recurring reconciliation. A point solution added to solve one problem creates another interface that must be maintained.
Each workaround makes the next change more expensive.
Evaluate the Next 100 Changes
Feature lists are a weak way to evaluate core banking software. Most vendors can demonstrate individual capabilities in controlled conditions. Banks need to understand how the platform behaves when the institution changes after implementation.
A better evaluation uses realistic operating scenarios. Ask the provider to demonstrate how the bank would:
- Configure and approve a new deposit product
- Change a fee, limit, eligibility rule, or workflow
- Introduce a new payment or fintech partner
- Trace a transaction from initiation through final settlement
- Distinguish pending, posted, ledger, and available balances
- Add an exception and route it for approval
- Connect a specialized third-party capability
- Export complete customer and account information
- Produce evidence showing who changed a rule and why
- Reverse a release or configuration that produced an unintended result
For each scenario, measure more than whether the capability exists. Determine how many systems are involved, which teams must participate, whether vendor intervention is required, how long the change takes, what it costs, how it is tested, and whether it creates a new manual process.
The financial model should reflect the expected volume of change over the full contract term. A five-year core decision should account for five years of new products, revised policies, integrations, regulatory requirements, acquisitions, customer expectations, and operating-model adjustments.
The bank is not buying a static system. It is buying the economics of every future decision it will make through that system.
A Modern Core Should Lower the Marginal Cost of Change
Modern core banking software should make each authorized change faster, safer, and less expensive than the one before it.
That requires a unified data model, real-time event processing, governed configuration, documented APIs, embedded controls, and clear auditability. Business teams should be able to configure routine changes within approved guardrails. Technology teams should be able to connect external capabilities without rebuilding the institution’s data foundation. Risk and compliance teams should be able to see how a rule was applied and who approved it.
No-code configuration is valuable when it reduces routine vendor dependency while preserving testing, permissions, segregation of duties, version history, and rollback. Without those controls, configurability simply creates a different form of operating risk.
AI should follow the same principle. Intelligence embedded within current data, policies, workflows, and permissions can help route work, identify exceptions, and support decisions. AI separated from the operating environment becomes another interface that must be reconciled and governed.
Specialized providers can still play an important role. The objective is not to eliminate every external capability. It is to make each addition deliberate, replaceable, and subordinate to an authoritative banking foundation.
This is the economic model behind adapfin’s Nucleus BankOS. It is designed to unify core banking, customer data, workflows, intelligence, and controls within one real-time operating environment. The institution retains the ability to configure products, connect selected partners, and evolve its operating model without turning every decision into a vendor project.
Control is not an abstract technology principle. It can be measured in the time, money, coordination, and permission required for a bank to act.
The most important question in a core evaluation may therefore be the simplest: after the platform is installed, how much will the next 100 changes cost?
adapfin Team
adapfin Technologies
Insights from the adapfin team.
See the platform behind the thinking.
See it with demo data, or join the founding-partner cohort.