Foundry · Consumer lending
Part of FoundryConsumer loans, decided inside your policy.
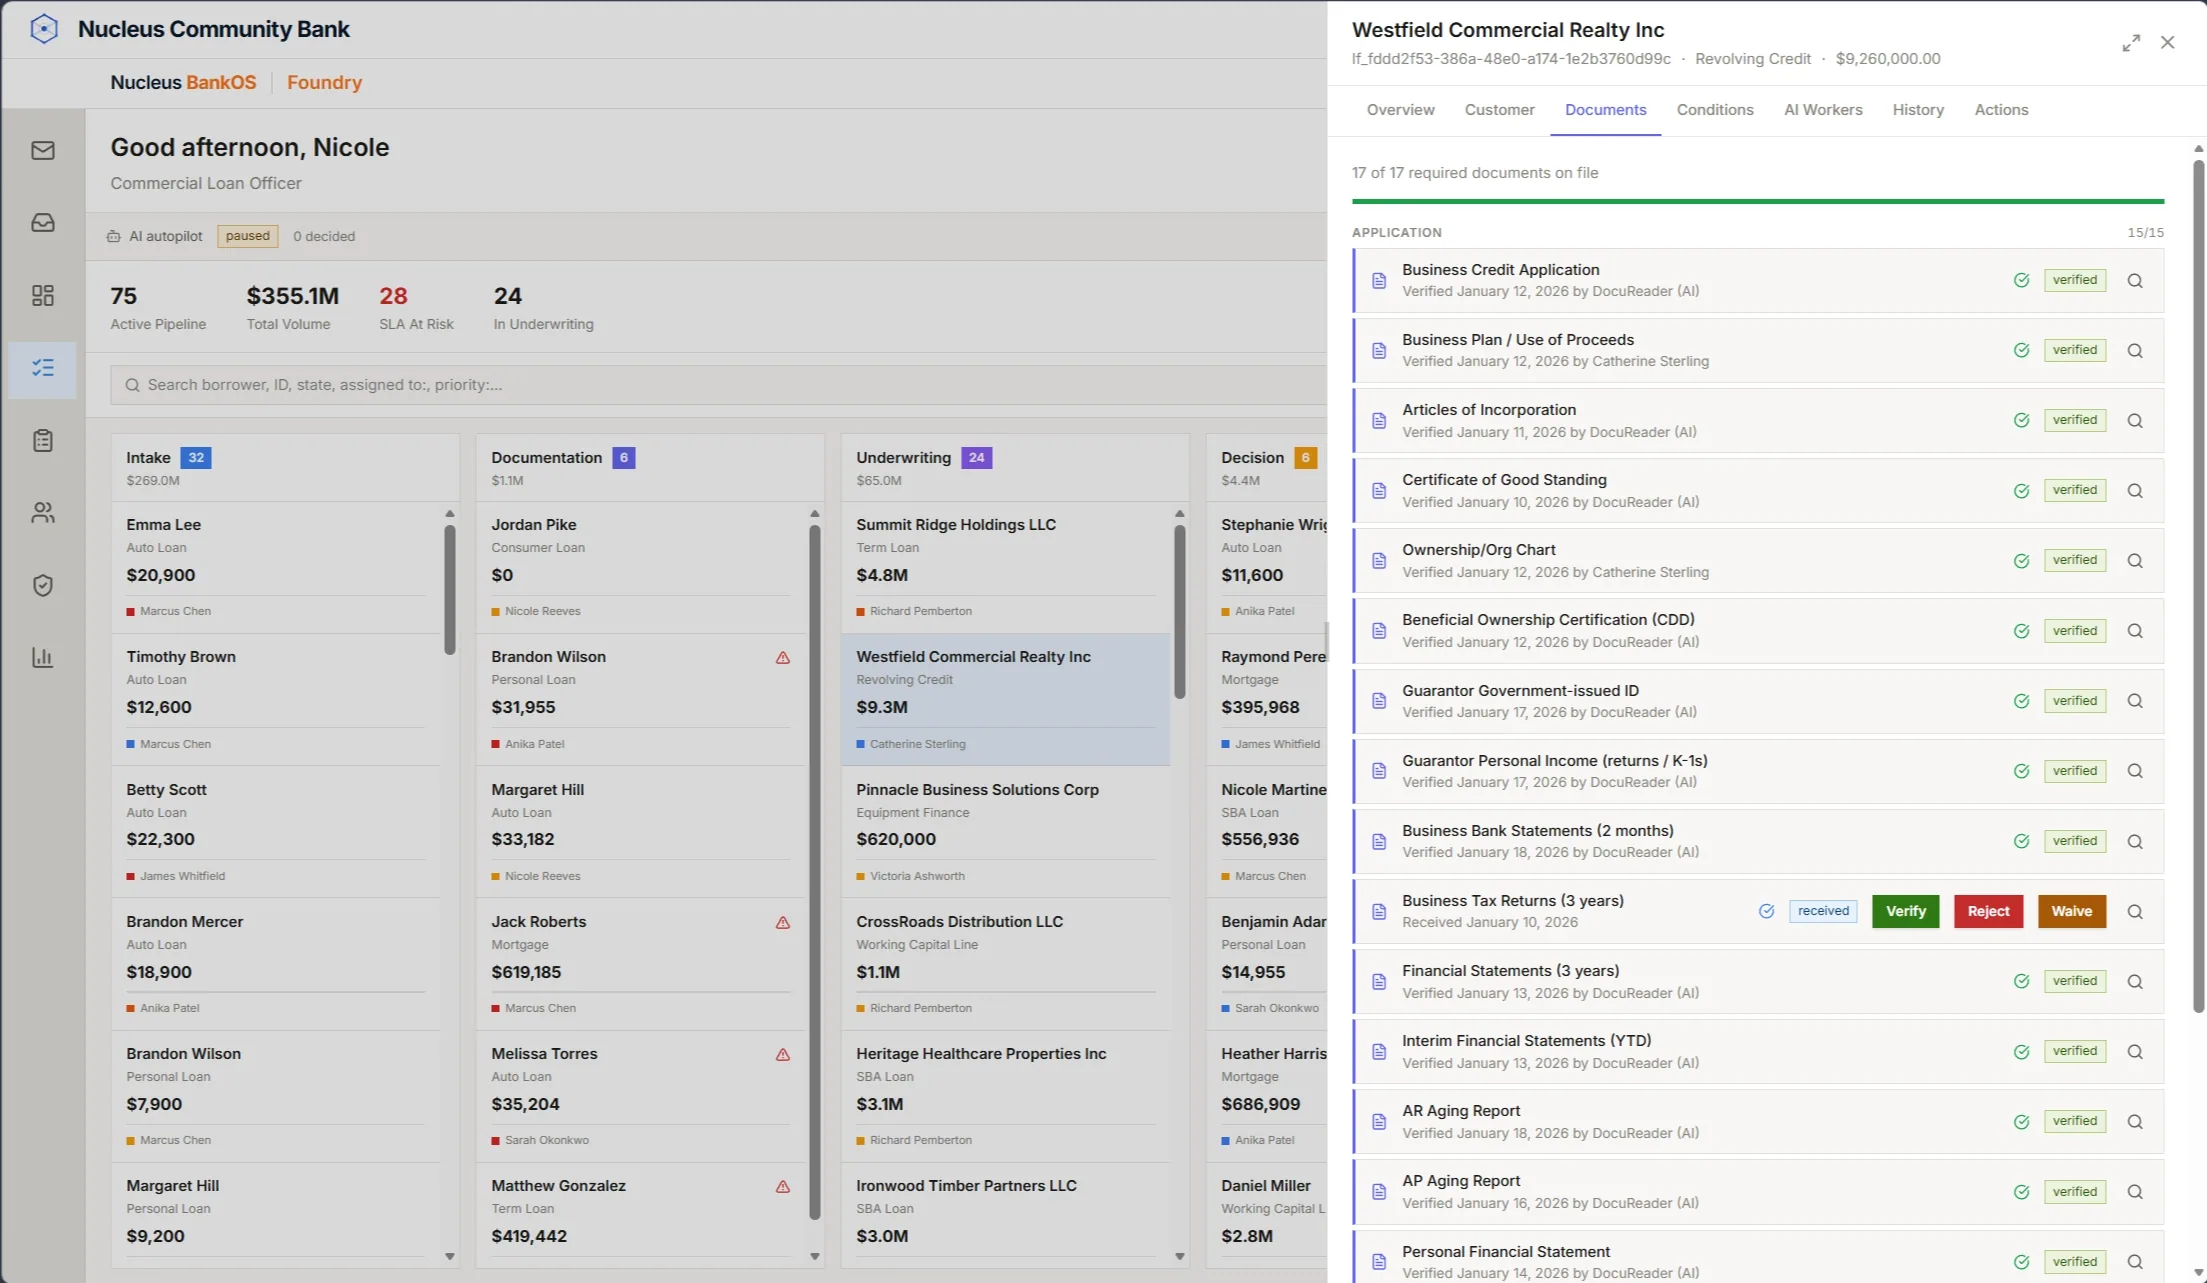
Foundry consumer lending originates, decides and services auto, personal, secured, mortgage and home-equity loans on Nucleus BankOS. AI workers decide routine files only within limits the bank sets; everything else goes to an underwriter.
At a glance
- Products
- Auto, personal, CD-secured, boat & RV, mortgage, HELOC
- Measures
- Credit score, DTI, LTV, loan-to-income
- Screening
- OFAC and synthetic-identity checks
- AI authority
- Products, dollar cap, tolerances, confidence: all bank-set
- Adverse action
- ECOA notice carrying the decision’s reasons
- After funding
- Servicing, escrow and 1098s on the same record
Specifications
Products, policy and the people who decide.
| Unsecured | Personal and debt-consolidation loans |
|---|---|
| Auto | New and used vehicles, with collateral value and loan-to-value |
| Secured | CD-secured, boat and RV |
| Residential | Mortgage and HELOC, with loan-to-value limits and escrow servicing |
| Policy | Minimums, ceilings and decision thresholds per product, configured by the bank |
|---|---|
| Ability to repay | Debt-to-income and loan-to-income checked against product ceilings |
| Outcomes | Decided straight through, referred to an underwriter, or declined with reasons |
| AI worker escalation | Over its dollar cap, outside tolerance, low confidence or product out of scope → underwriter |
| Final say | A person’s decision on an escalated file is final; the AI does not revisit it |
| Channels | Officer-entered applications and partner loan files from point-of-sale and fintech channels |
Questions
Consumer lending: what banks ask
What consumer loans can Foundry originate?
Auto (new and used), personal and debt-consolidation, CD-secured, boat and RV, mortgage and home equity lines of credit. Each product has its own policy rules, set by the bank.
Can AI decide consumer loan applications?
Only within limits the bank sets. An AI worker decides a file only when the product, amount, ratios and its own confidence are inside the authority the bank gave it; otherwise it names the limit it hit and hands the file to an underwriter, whose decision is final.
How are consumer adverse action notices produced?
Every decline carries the specific reasons it was reached. The ECOA notice is generated at decline, routed to the assigned officer, and sent when the officer closes the file.
Can point-of-sale or fintech partners send applications?
Yes. Partners submit a standard loan file through the intake API and it enters the bank’s own pipeline and policy. They follow status and decisions by webhook but never see the bank’s internal queues.
Does Foundry service mortgages and HELOCs?
Yes. Schedules, payment allocation, escrow for taxes and insurance, delinquency, modifications, statements and year-end 1098s all run on the same loan record.
Bring your consumer credit policy.
We will walk through how your products, limits and escalation paths would be set up in Foundry.