Foundry · Commercial lending
Part of FoundryCommercial credit, watched after it closes.
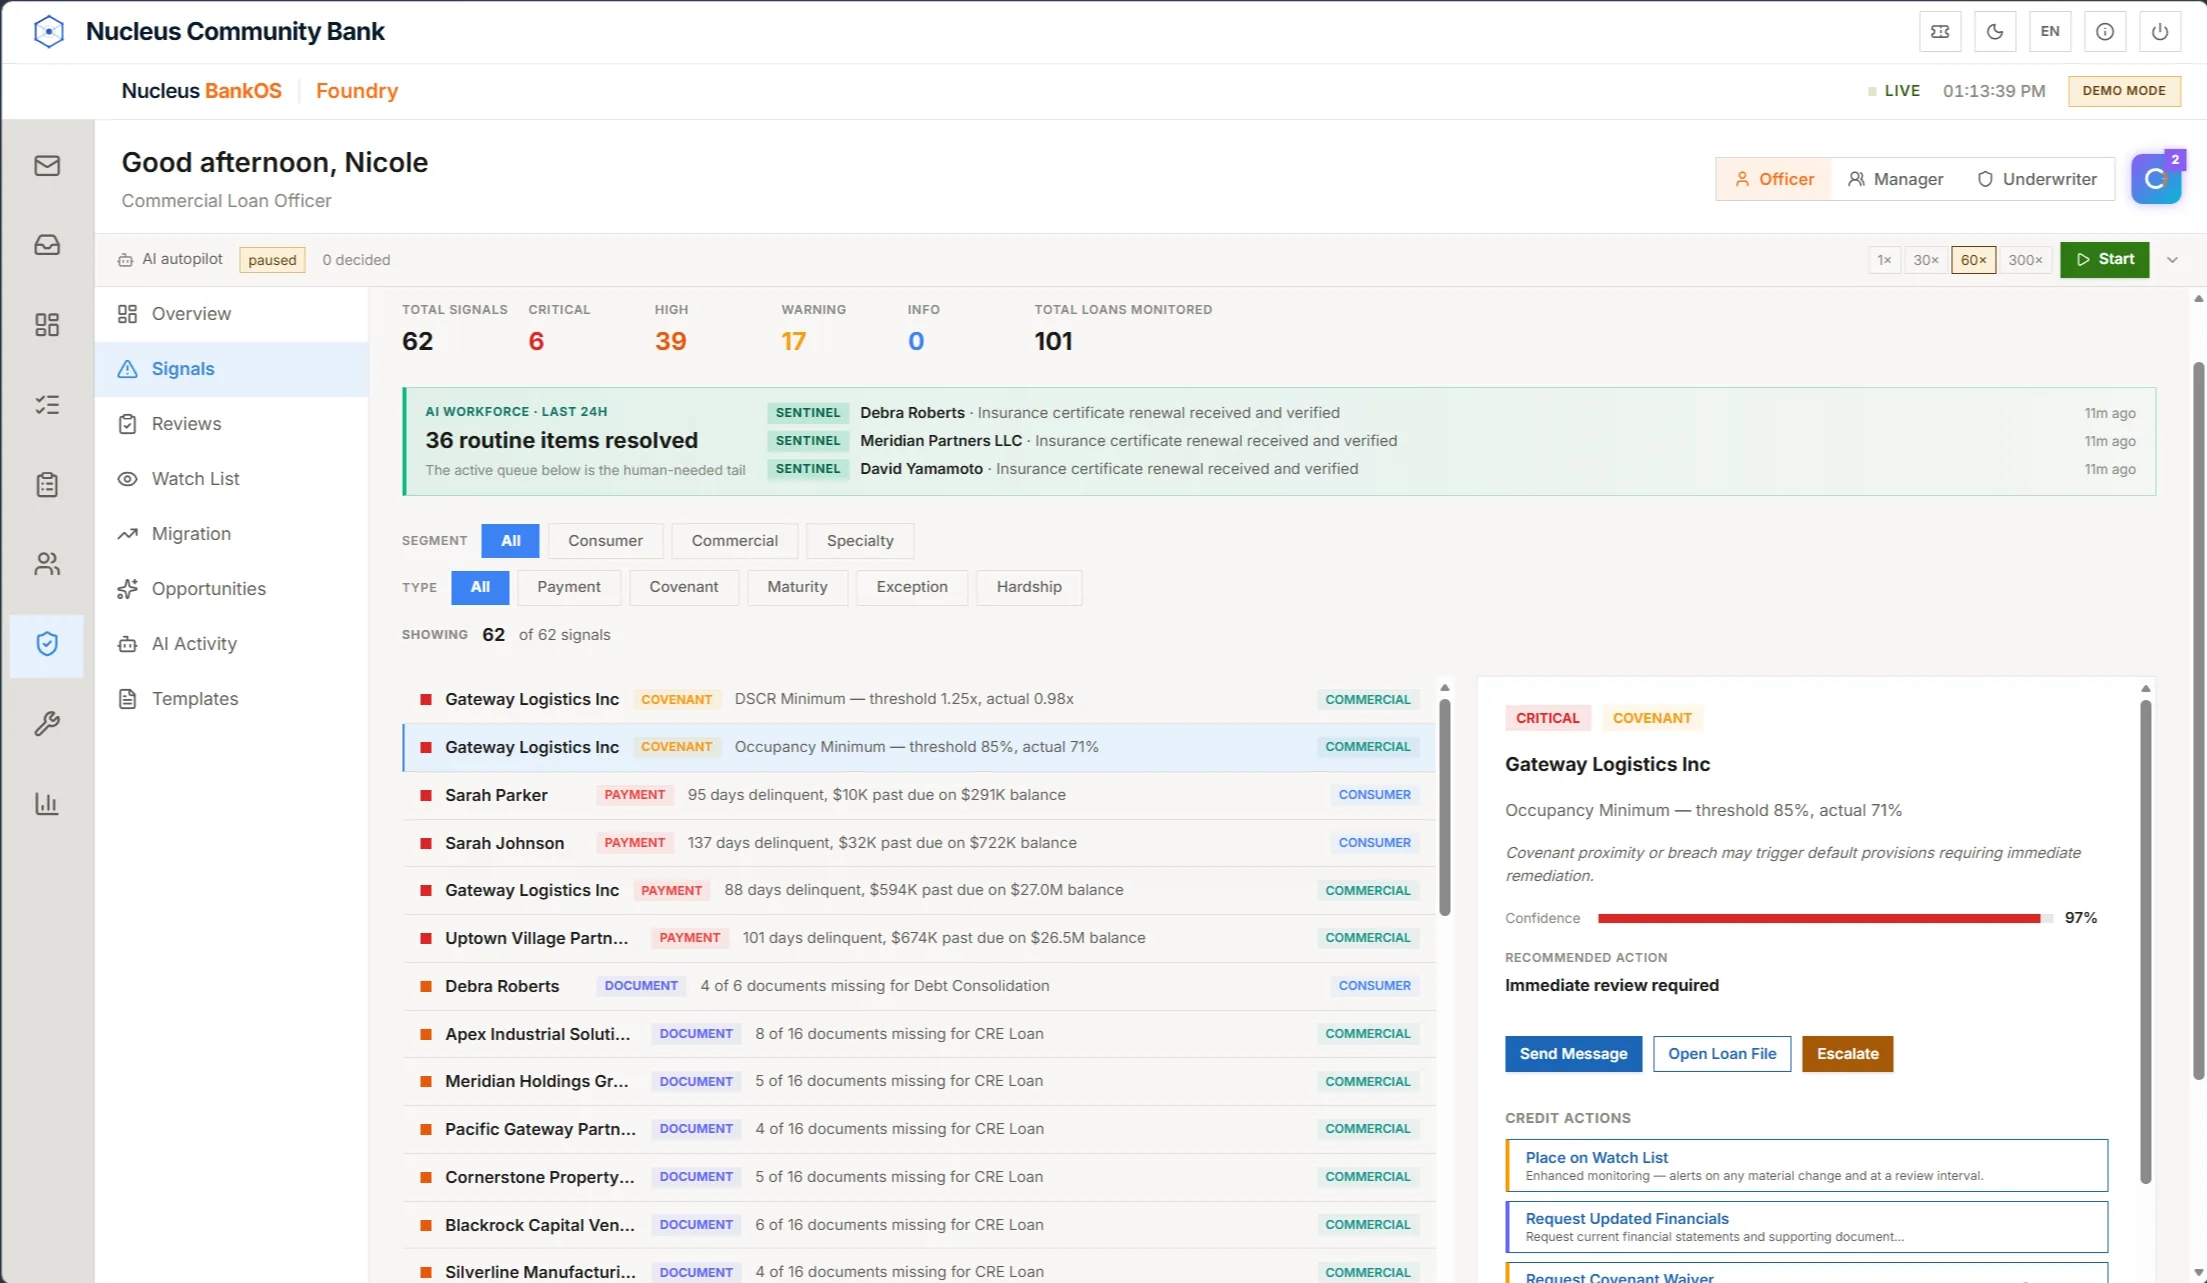
Foundry commercial lending handles C&I, commercial real estate, SBA, asset-based and structured credit on Nucleus BankOS. AI prepares the analysis, officers decide under the bank’s approval authority, and covenants and risk grades are tracked on the live loan.
At a glance
- Products
- C&I term, lines of credit, CRE, construction, SBA, equipment
- Structured
- Asset-based, bridge, mezzanine, participations, syndication
- Measures
- DSCR, loan-to-value, revenue, credit score
- AI assistance
- Spreading, document and covenant extraction, memo drafts
- Monitoring
- Covenants, borrowing bases, risk grades
- Workout
- Restructure, forbear and recover in one workflow
Specifications
From term loans to structured credit.
| Commercial and industrial | Term loans, working capital and revolving lines of credit |
|---|---|
| Commercial real estate | Owner-occupied and investor CRE, construction |
| SBA | 7(a) and 504, with guarantee processing |
| Equipment | Equipment finance with lien recording |
| Asset-based | ABL revolvers, receivables and inventory finance, CRE bridge |
| Structured | Mezzanine, unitranche, participations and syndication, with cash-flow waterfall modeling |
| Debt-service coverage | From NOI for real estate and EBITDA for C&I, against total annual debt service |
|---|---|
| Policy limits | Minimum DSCR and revenue, maximum loan-to-value, per product |
| AI-prepared analysis | Financial spreading, document and covenant extraction, credit-memo drafts for officer review |
| Covenants | Tracking dashboard with violation alerts and a remediation workflow |
| Borrowing bases | Asset-based lines monitored against periodic borrowing-base updates |
| Risk grades | Grade migration and watchlists driven by early-warning signals |
Questions
Commercial lending: what banks ask
What is commercial loan origination software?
It takes business credit from application through underwriting, approval and closing. Foundry does this for C&I, commercial real estate, SBA and asset-based loans, then services and monitors them on the same record.
How does Foundry calculate DSCR?
Debt-service coverage is net operating income for real estate, or EBITDA for C&I, divided by total annual debt service including the new loan. It is checked against the minimum the bank sets for each product.
How does Foundry monitor loan covenants?
Covenants extracted at origination are tracked on the live loan. A violation raises an alert and opens a remediation workflow for the relationship team.
Does Foundry support SBA lending?
Yes. SBA 7(a) and 504 are product categories with their own policy rules, and guarantee processing is built in.
What does AI do in commercial underwriting?
It prepares the file: spreading financials, extracting data and covenants from documents and drafting the credit memo. The officer reviews it and the decision is made under the bank’s approval authority.
Can a community bank lead a participation or syndication?
Foundry supports participations and syndicated facilities with structuring and risk tracking, so a bank can lead a facility as well as join one.
Bring a commercial deal you had to pass on.
We will walk through how Foundry would structure, underwrite and monitor it on your policy.